Waterfront residences, rental properties, vessels, private aviation, collections, reputation, and legacy. Clear education, in Spanish and English, backed by verifiable data.
For families, family offices, and the advisors who serve them
of U.S. homes are underinsured, per CoreLogic, lacking enough coverage to fully rebuild after a loss.1
of policyholders who lost their homes in the 2021 Marshall Fire in Colorado were underinsured; 36% severely.2
was the average NFIP flood claim payment from 2020 to 2024 ($63,691, per FEMA). A single inch of water can cause $25,000 in damage.3
registered vessels make Florida the national leader, and also the state with the most boating deaths in recent U.S. Coast Guard reports.4
It is not a lack of capacity or vision. It is that no one explained these tools to our community in its own language, and inherited ideas about insurance and protection stayed small while today's estates grew large. Tap each myth to see the reality.
Adjusted for inflation, median wealth of Hispanic families in the U.S. more than tripled between 2013 and 2022, from about $18,000 to $61,600. Meanwhile, life insurance ownership among Hispanics fell from 51% in 2021 to 40% in 2025, lower than any other ethnic group.5
Insurance is an expense. I would rather invest that money.
The reality: 72% of Hispanics overestimate what a term life insurance policy costs.6 And the math of a large estate is simple: a single lawsuit or a single storm without adequate coverage can erase years of investment returns. Protection does not compete with investing; it is what makes it last.
These things get handled within the family, the way they always have.
The reality: family solidarity is one of the great strengths of our culture, and it works for many things. But no family network can absorb a five-million-dollar lawsuit, the rebuild of a waterfront home, or a disorganized succession across two countries. Large estates require structures that match them, not just goodwill.
I already have a CPA and an attorney. I am covered.
The reality: only 34% of Hispanics work with a financial professional,6 and even those who do often have advisors who never talk to each other. The CPA optimizes taxes, the attorney builds structures, but no one checks whether policy limits grew along with the estate. Gaps live precisely in the spaces between advisors.
Life insurance is for funeral expenses.
The reality: 26% of Hispanics feel life insurance is only for covering final expenses.6 In large estates, life insurance serves very different purposes: providing immediate liquidity so the family never has to fire-sell properties or businesses, equalizing inheritances among children, and funding the continuity of the family enterprise. It is a tool of estate Architecture, not a funeral expense.
Once wealth passes the million-dollar mark, protection stops being a policy and becomes an Architecture. Each domain has its own rules, its own hidden limits, and its own typical gaps. Open each one and find yours.
Standard policies are designed for standard lives. If any of these lines sounds like the conversations at your table, your lifestyle has probably outgrown your protection. Beneath each one, what few people tell you.
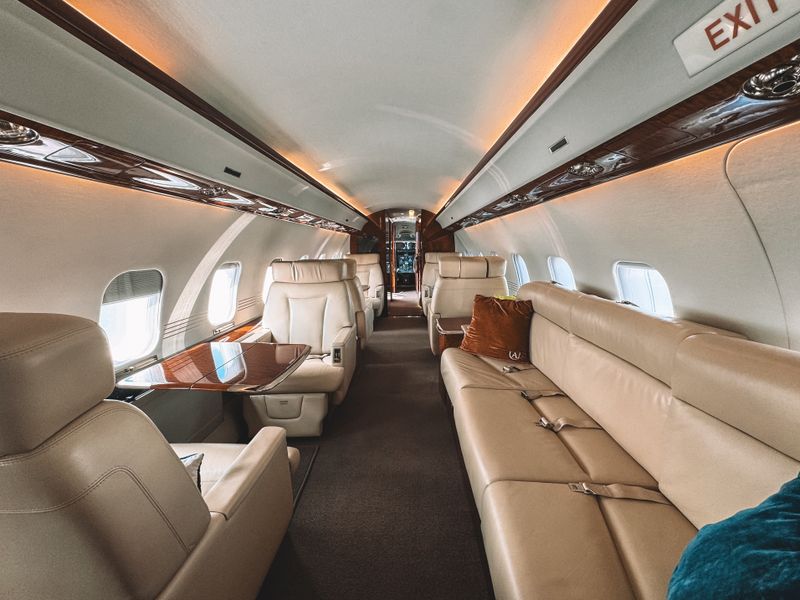
We split the year between Miami and Madrid. The grandchildren ski with us every winter.
What few tell you: policies carry territorial limits, and property abroad is rarely covered by a U.S. policy. An international medical evacuation can cost tens of thousands of dollars or more, and specific travel and worldwide liability coverage exists for families living across two countries.
Saturdays we take the boat out to Elliott Key. The boys bring the PWCs.
What few tell you: personal watercraft (PWCs) were 17% of Florida's registered vessels in 2025, but 23% of reportable accidents.4 Florida law generally places liability on whoever is operating, but the owner can still be liable if aboard or if they lent it to someone unprepared to handle it. Each vessel needs its own policy and its own line on the umbrella.
Our daughter trains in Wellington. This year she qualified for the winter circuit.
What few tell you: a competition horse can be a six-figure asset that a home policy typically does not cover. Equine mortality and surgical coverage exist, and the liability if the animal injures someone at the barn or in transport requires its own protection.
The collection began with my father's watch. Today it is fourteen pieces, and each one has its story.
What few tell you: a typical home policy caps jewelry theft at about $1,500 (generally $1,000 to $2,000).7 A serious collection is protected piece by piece, at agreed value, with appraisals updated every 3 to 5 years and coverage in transit, which is where most pieces are lost.
The Islamorada house rents out the weeks we are not using it. It practically maintains itself.
What few tell you: nightly rentals turn the home into a business, and many home policies exclude or void coverage during short-term rentals. Specific vacation-rental insurance exists. Without it, an injured guest files their claim directly against the family's estate.
More agreements have closed in our stadium suite than in any boardroom.
What few tell you: in Florida, serving alcohol to adult guests, in the suite, on the yacht, or at the year-end celebration at home, generally does not make you liable for what they do afterward. The exceptions matter: knowingly serving anyone under 21, or someone you know is addicted to alcohol, can make you liable if they later cause harm, and outside Florida the rules change. Even a baseless lawsuit costs money to defend, and an umbrella usually includes that defense.
Eight full guides, a glossary in both languages, and printable tools. Everything checked against sources, free, with no sign-up.
Homes and hurricanes, flood, auto, boats, aviation, collections, umbrella, and household staff.
The terms in your policies, in English with their Spanish equivalent.
Short answers to what Florida families ask most.
Printable: season preparation and the map of where everything is.
Explore the domains, the myths, and the stories at your pace, in your language. No sign-up, no emails, no pressure.
The Protection Map shows you where your risk awareness has blank spots. Anonymous by design.
If the material raises questions, write to me. And when a topic requires a licensed professional, I will say so clearly and connect you with the right one.
Twelve questions across the risk zones of your family. At the end you will see your awareness level and the domains where your map went blank. We ask for no figures or personal data.
Your answers are already saved. Write to me in the form below and they will arrive attached to your message, along with what I would review first in your blank zones.
Continue to the form ↓Nothing leaves your browser until you send the form.
This self-assessment is an educational reflection tool. It does not constitute insurance advice or an analysis of your policies, and it does not replace a review by a licensed professional. Your answers are saved only in your browser, so you can pick up where you left off, and are not sent anywhere unless you choose to send them with your name and email.
I am Christian R. González, from Miami, bilingual from birth and a graduate of Florida International University. My career began in the insurance industry: for nearly two years I helped more than one hundred families protect their loved ones, and I trained new agents on how to explain these subjects clearly. That is where I understood something I have never forgotten: our community is almost never taught these tools in its own language, and that lack of clarity costs Wealth.
I then spent years in live events and stadium operations, working from the inside on the execution of more than a thousand events, from private celebrations to full season operations at a Major League ballpark. That chapter gave me the discipline I now apply to wealth risk: events that go well do not depend on luck; they depend on having thought, in advance, about everything that could go wrong. Today I practice as a licensed Florida agent dedicated to private-client risk for high-net-worth families. This space is my way of giving the community the clarity it deserves.
Christian R. González
Licensed agent · Florida Lic. #W606240
View my LinkedIn profile ↗If the self-assessment left you with questions, if one of the stories felt familiar, or if you would like me to cover a particular topic, write to me. We can meet in person in South Florida or by video call from anywhere in the state, in whichever language you prefer.
I reply personally, usually within 48 hours. I will only write to you if you write to me first. The profile fields are optional; they help our first conversation arrive prepared.
Thank you for writing. I will reply personally very soon.